There are more ways than ever to move money internationally.
Wise. Revolut. Traditional banks. SWIFT. FX providers. Regulated crypto and digital-asset providers.
For someone buying a €500,000, €1 million or €2 million property abroad, the problem is therefore not necessarily:
“How do I move the money?”
The harder question is:
“Who makes sure everything around that money works together until the transaction is actually completed?”
Moving €1 million is only one part of buying a €1 million property
Consider a buyer based abroad purchasing a property in Italy.
The buyer may have the funds readily available. They may already have a bank, an FX provider, or a digital-asset provider.
But the transaction can still involve:
- buyer identification and readiness
- source-of-funds documentation
- property documentation
- seller verification
- lawyers
- notaries
- banks
- currency conversion
- payment instructions
- contractual milestones
- tax and registration requirements
- completion and handover
Each party may be doing its own job correctly.
The problem is that nobody may be responsible for making the entire sequence work from the buyer's perspective.
Wise can move the money. That doesn't mean the transaction is ready.
Wise can be useful for international transfers and currency conversion.
But knowing that you can transfer €1 million does not tell you:
- when the currency should be converted;
- which payment should happen first;
- whether the seller's details have been independently verified;
- whether the legal documentation is complete;
- whether the payment corresponds to the correct contractual milestone;
- what happens if one of the other parties is not ready.
The transfer is a component of the transaction.
It is not the transaction itself.
Revolut can make international banking easier. It doesn't remove transaction fragmentation.
Modern financial accounts have made holding multiple currencies, exchanging money and making international payments considerably easier.
But the property transaction still exists outside the account.
Your lawyer is somewhere else.
Your notary is somewhere else.
The seller is somewhere else.
The property documentation is somewhere else.
The completion date is somewhere else.
And the buyer can still end up being the person connecting all of those pieces.
SWIFT can transmit the payment. It doesn't know what the payment is supposed to accomplish.
SWIFT is financial messaging infrastructure. Banks use it to communicate payment instructions and other financial information.
But a SWIFT message does not know whether the property documents are complete.
It does not know whether the seller has been properly verified.
It does not know whether the lawyer has completed the required work.
It does not know whether the buyer is ready for completion.
The payment can successfully arrive while the transaction itself remains incomplete.
A crypto exchange can convert the asset. It doesn't complete the purchase.
For a buyer whose wealth originates in digital assets, the path may look different:
Digital assets → regulated provider → fiat → bank → property transaction.
The conversion from crypto to fiat may be handled efficiently.
But the buyer still has a property transaction to execute.
There may be questions around documentation, source of funds, payment sequencing, legal parties and completion.
Converting the asset solves the conversion problem.
It does not solve the transaction problem.
So who owns the gaps?
This is where high-value cross-border transactions become different from ordinary payments.
The bank has its responsibilities.
The FX provider has its responsibilities.
The lawyer has its responsibilities.
The notary has its responsibilities.
The seller and buyer have their responsibilities.
And the property professional has theirs.
But between these responsibilities are gaps.
Someone has to make sure the right thing happens, with the right party, at the right point in the transaction.
Without that person or function, the buyer becomes the project manager.
This is the problem Paycre addresses
Paycre is not another way to send money.
It is not a bank, an FX provider or a crypto exchange.
And it does not replace the lawyer, notary or other professionals involved in a property transaction.
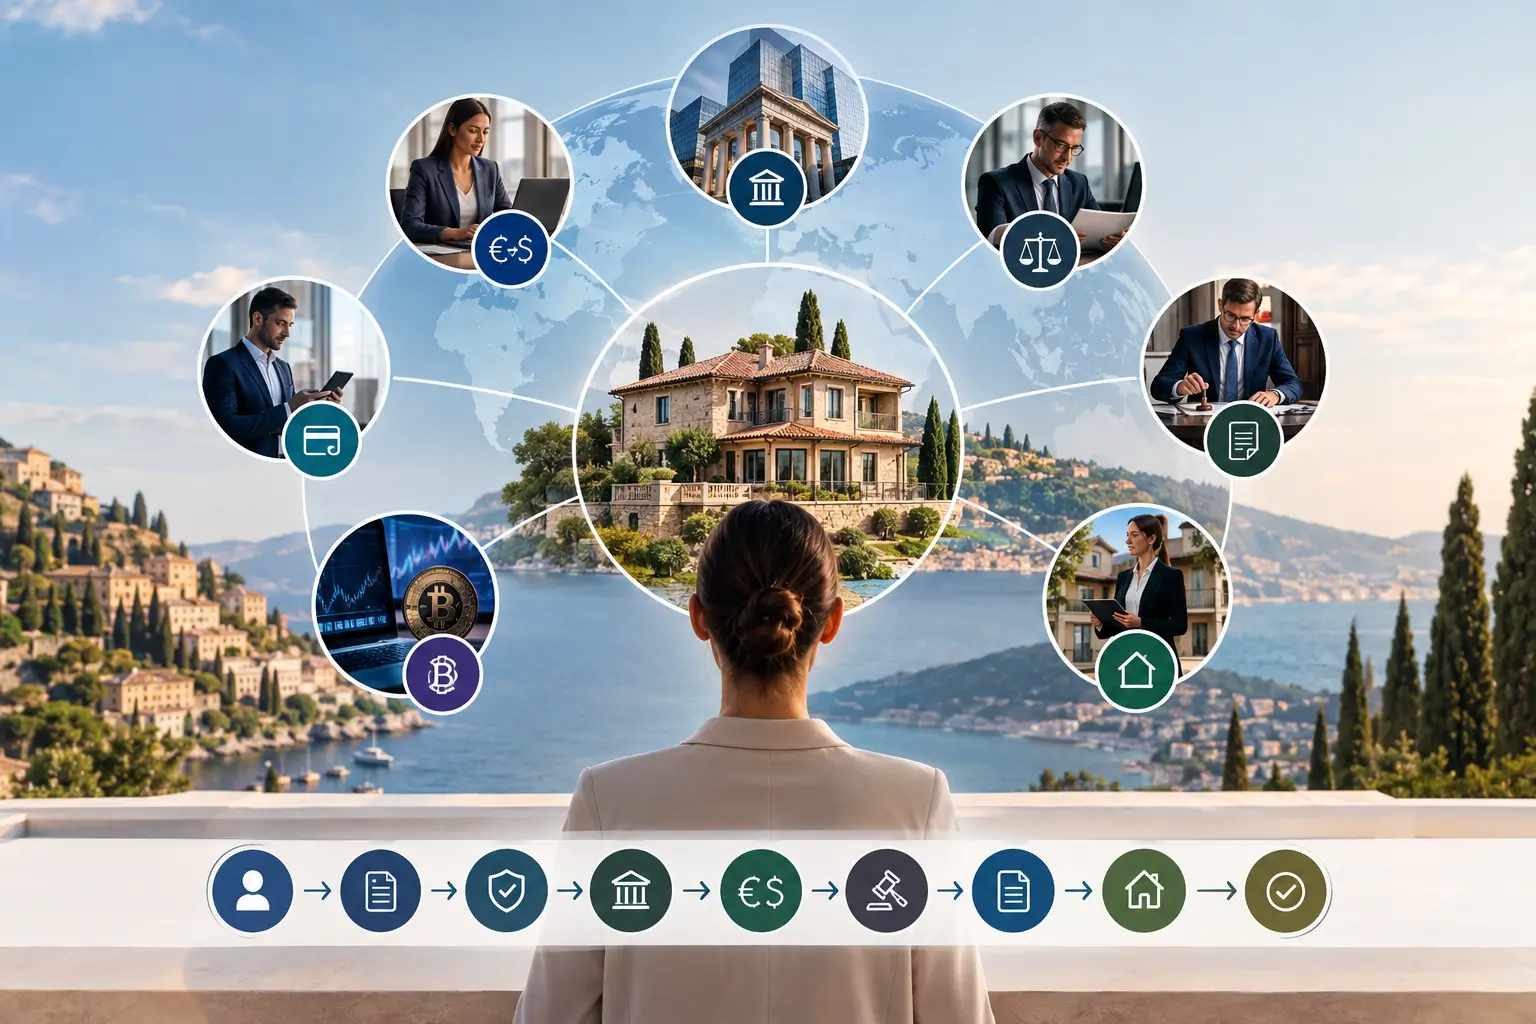
Its role is to take responsibility for the execution layer between them.
That means establishing what needs to happen, who needs to do it, what information is required, which milestone comes next and whether the transaction is actually ready to move forward.
The financial provider can move the funds.
The lawyer can handle the legal work.
The notary can handle the notarial act.
The property professional can handle the property side.
Paycre makes those pieces operate as one transaction from the buyer's perspective.
The buyer is not buying another payment app
This distinction matters.
A buyer purchasing a €1 million property abroad does not necessarily need another account.
They need someone who understands that the €1 million is attached to a real-world transaction with a beginning, a sequence of conditions and a completion.
The question is not:
“Which app should I use to send the money?”
The question is:
“Who is making sure my money, my property, my legal process and all the parties involved actually converge at completion?”
The missing layer in cross-border transactions
Financial infrastructure has become faster.
Property discovery has become digital.
Currency conversion has become easier.
Digital assets have become transferable across borders.
Yet the transaction connecting all of these systems can remain fragmented.
That is the gap Paycre is built around.
Not another way to move €1 million.
A way to make sure the €1 million actually gets the deal done.
Paycre provides transaction support and coordination for high-value cross-border property transactions, connecting buyers with the relevant property, legal, notarial, FX and financial infrastructure required to complete the transaction.
Paycre does not hold or move client funds. Fund movements remain with the appropriate regulated financial providers.